What the Victorian ‘Gauge War’ during the explosive growth of the railways tells us about the AI readiness gap in B2B technology channels.
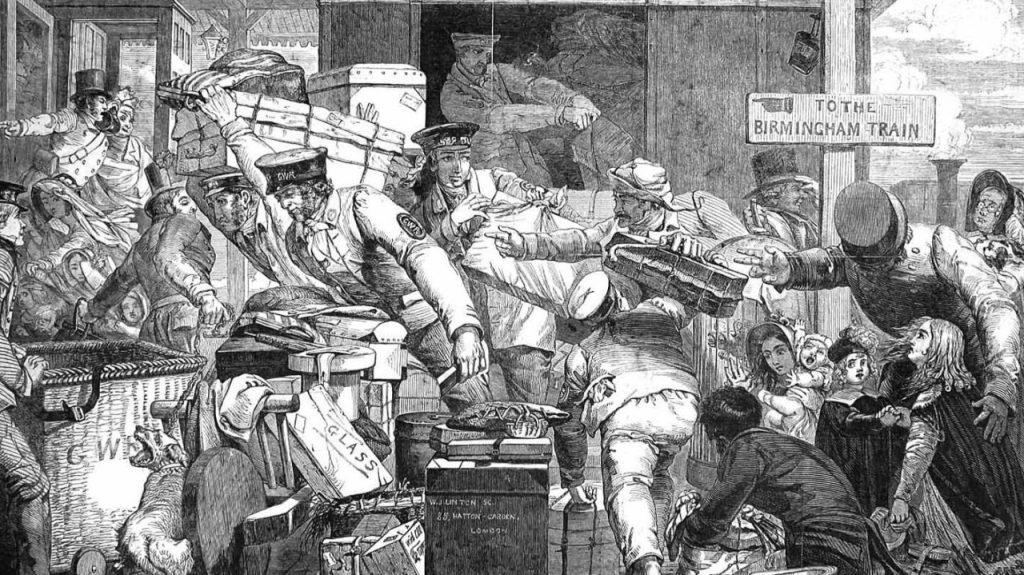
In the 1840s, Britain’s railway companies built their networks to incompatible standards. Brunel’s Great Western Railway ran on a magnificent seven-foot broad gauge, smoother, faster and technically superior to the four-foot-eight-and-a-half-inch standard gauge spreading across the rest of the country. The problem was not the technology. It was that the two systems could not talk to each other. At junction points, passengers had to change trains and freight had to be manually transferred (see the cartoon in our heading), an expensive, time-consuming and entirely avoidable friction that multiplied with every mile of new track laid to the wrong specification. Parliament eventually mandated a single standard. In 1892, the Great Western converted 171 miles of broad-gauge track in a single weekend, one of the most dramatic and costly forced reinventions in industrial history.
Accenture ‘s latest research report, From Early Impact to Enduring Advantage (2026), leans into this transport and interchange metaphor, referencing the “intelligent superhighway” that enterprises must construct if AI is to move at the speed it is capable of, rather than the speed of the infrastructure beneath it. The authors, drawing on a survey of 3,650 executives across 20 industries and 20 countries, are writing for enterprise buyers. But the gauge war they are describing has a second front that most B2B technology vendors have not yet recognised as their own.
Broad gauge in a standard gauge world
The Accenture findings are stark. Some 86% of organisations plan to increase AI investment in 2026. Most believe it will contribute positively to revenue growth. Yet only 21% have redesigned end-to-end processes with AI at the core. Around 70% of technology budgets still fund legacy systems. Fewer than one in five organisations have modernised their data, platforms, governance and talent systems sufficiently to support broad AI deployment. Only 16%, those with mature cloud foundations and strong governance guardrails, are positioned to capture the compounding benefits that agentic AI delivers.
The three-phase maturity model at the heart of the report, Siloed AI, Structural AI, Systemic AI, is essentially a gauge specification. Siloed AI is broad gauge: technically functional within its own territory, but incompatible with the wider network. Systemic AI is the adopted standard: the architecture to which the enterprise operating model, the data infrastructure and, critically, the partner ecosystem must conform if intelligence is to move freely across the entire value chain.
Most of the channel community is running broad gauge. The problem is that the standard beneath the market is shifting, and the cost of arriving late to that realisation is not inconvenience. It is structural obsolescence.
The majority of MSPs, VARs and resellers sit, by any honest assessment, at Stage 1 or early Stage 2 of Accenture’s model: AI applied at the task level, primarily for internal efficiency, with literacy measured through training completion rather than operating model change. That is not a criticism of their technical competence. Brunel’s broad gauge was genuinely superior in isolation. The problem is that the standard beneath the market is shifting, and the cost of arriving late to that realisation is not inconvenience. It is structural obsolescence.
‘All Change Please!’
Accenture identifies one specific point in the enterprise where the friction concentrates, and it is worth noting closely. The process, the report observes, breaks the moment it collides with adjacent systems or when the enterprise needs to interact with suppliers and partners. Too often, these interactions still occur through email or informal conversations, leaving them invisible to intelligent systems.
That is a precise description of the gauge break station: the point where the smooth broad-gauge line meets the rest of the network, and everything has to stop, be manually transferred and restart. In most vendor channel ecosystems today, that station is everywhere. Deal registration portals that exist outside the customer’s data architecture. MDF claim processes are conducted on spreadsheets. Partner business reviews are built around activity metrics that bear no relationship to the outcomes the customer’s board is now measuring. The informal knowledge of experienced partner managers that has never been codified, structured or made legible to the agentic systems customers are now building around it.
Partners are not failing. The gauge is wrong.
The conversion problem
The Victorian gauge war was resolved, eventually, by parliamentary mandate and a single extraordinary weekend of mass conversion. No such mechanism exists in technology markets. The equivalent pressure comes from customers who, under instruction from their boards, their consultants and their own competitive anxiety, are advancing through Accenture’s maturity phases and finding that the vendor relationships they rely on cannot keep pace.
This is where the implications for partner programme design become unavoidable. Accenture reports that only one-third of executives say their talent strategy is fully integrated with their AI strategy. More than 40% report upskilling employees, but fewer than 10% are redesigning roles or responsibilities. The distinction matters enormously. A partner that has certified its staff in AI tools but has not redesigned its service model, its pricing structure, its technical team composition or its customer engagement approach has not converted its gauge. It has repainted its carriages.
Vendor partner programmes that respond to this moment by adding AI specialisation tracks and updated certification requirements are making the same mistake. The constraint is not knowledge of AI tools. It is the operating model change required to use those tools in ways that make sense at the scale and integration depth that Systemic AI demands. Accenture is explicit: meaningful financial impact takes twelve months or more to appear even after architectural modernisation begins. Organisations at the Siloed phase can take two to three years to produce measurable value. Partners and the vendor programmes that support them are being asked to close that gap for customers whose patience is shortening by the quarter.
Standard gauge or stranded stock?
Accenture introduces a framework it calls buy, build and boost, the three modes through which technology organisations should engage ecosystem partners in their AI transformation. Buying ready-made components from partners accelerates time to market. Building is reserved for proprietary capabilities that create a genuine competitive advantage. Boosting, layering proprietary data, ontologies and workflows onto partner platforms, offers a third path. The goal is to maximise value without reinventing the entire stack.
It is a commercially astute framework. It is also an implicit specification for what a capable channel partner now needs to be. Buy, build and boost are not the language of a rebate programme. They are the language of a co-innovation relationship, structured around shared outcomes, governed by shared metrics, and built on a joint value proposition that can survive a C-suite conversation about AI strategy.
Most partner programmes were not designed to enable that kind of relationship. They were designed to move product efficiently, at scale, with appropriate incentives and minimal friction. That design was rational for the market it served. The gauge it specified is no longer compatible with the network being built around it.
The cost of delay
The 1892 conversion was expensive precisely because the broad-gauge network had been allowed to grow for decades before the reckoning arrived. Accenture makes the same point in the language of technology strategy: the choices organisations make now create path dependencies that compound for years. Once an enterprise has built its intelligent superhighway in a particular direction, reversing course becomes prohibitively expensive. The “wait and see” posture that feels prudent is, the report concludes, the most dangerous option available.
That warning was written for enterprise buyers. It applies with equal force to the vendors who serve them through indirect channels, and to the programme leaders responsible for the design of those relationships. The vendors who continue to lay broad-gauge track , designing partner programmes for a Siloed world while their customers accelerate toward Systemic AI , will find their ecosystems doing what railways always do when the gauge is wrong. Traffic diverts to a network that runs on the right standard.
The equivalent of the GWR ‘conversion weekend’ of 1892 is coming. The question is whether yours will be planned or forced.
Accenture, “From Early Impact to Enduring Advantage: The Intelligent Superhighway You Need to Unlock Value from AI” (2026). Authors: Manish Sharma, Chief Strategy and Services Officer; Senthil Ramani, Chief Offerings and Products Officer. Research base: Pulse of Change survey, January 2026, n=3,650 executives, 20 industries and 20 countries, supplemented by analysis of approximately 6,000 AI client engagements. Full report at accenture.com/research.
